
Tesla’s investment value cannot be judged by deliveries alone. Third-quarter 2026 results were released on October 21. Operating income increased from the previous quarter but declined year over year. Free cash flow returned to positive territory. CoinPop’s view is that there is now reason to consider both the potential for business expansion and profitability and investment burdens, but it is difficult to conclude that the stock is undervalued without comparing the latest price with future cash generation per share.
Subject of analysis: Tesla, Inc. common stock (NASDAQ: TSLA) · Prepared: 2026-10-13 · Updated and official materials verified: 2026-10-26 KST · Edited and verified by: CoinPop Editorial Team. This article is general investment information, not a personalized recommendation to buy or sell. Financial results are for the relevant fiscal period, and the valuation examples below are computational assumptions, not actual stock prices, market forecasts, or price targets.
1. Tesla’s third-quarter deliveries: beating expectations and declining year over year can both be true
Tesla announced its third-quarter operating figures on 2026-10-02. The starting points for comparison are the actual production and delivery announcement, the company-compiled analyst estimates dated 2026-09-29, and the announcement for the same period last year. The fact that the company compiled the estimates does not mean it guaranteed them or adopted them as its own guidance.
| Metric | Actual, Q3 2026 | Comparison basis | CoinPop calculation and interpretation |
|---|---|---|---|
| Vehicle deliveries | 486,532 vehicles | Company-compiled average estimate: 461,974 vehicles | 24,558 vehicles, about 5.32% above estimate |
| Deliveries versus previous quarter | 486,532 vehicles | 480,126 vehicles in Q2 2026 | Up about 1.33% |
| Deliveries versus same period last year | 486,532 vehicles | 497,099 vehicles in Q3 2025 | Down about 2.13% |
| Difference between production and deliveries | Production: 464,391 vehicles | Deliveries: 486,532 vehicles | Deliveries exceeded production by 22,141 vehicles |
| Energy storage deployments | 13.7 GWh | Company-compiled average estimate: 15.9 GWh | 2.2 GWh, about 13.84% below estimate |
Percentage changes are calculated as “actual ÷ comparison value − 1” and rounded to two decimal places. Delivery estimates were compiled from 24 firms, and storage deployment estimates from 19. The percentage by which results beat estimates can also vary if consensus figures from different aggregators are mixed. Beating estimates means performing better than those estimates; it does not mean year-over-year growth or higher profits.
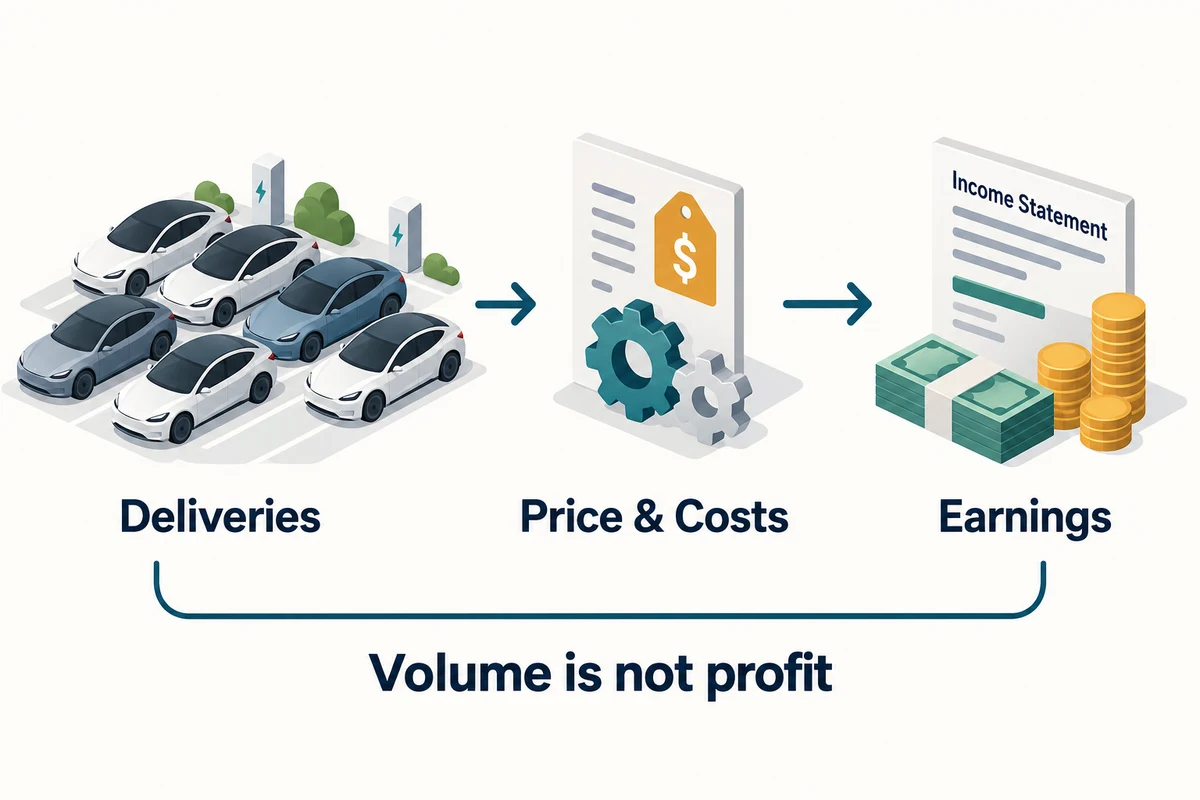
The fact that deliveries exceeded production is a reason to examine changes in inventory and vehicles in transit. However, that difference alone does not establish that ending inventory fell by exactly the same number of vehicles or that cash flow improved. Inventory scope, delivery recognition, regional logistics, and working capital should be verified in the actual financial statements.
Report confirmation: Tesla IR’s October 21, 2026 earnings release and the Q3 2026 Update attached to the 8-K confirm that financial results for the quarter ended September 30 were released. The quarterly results and cash flows below are reported actual figures and should be distinguished from future guidance.
2. Tesla investment analysis should separate automotive, energy, and future businesses
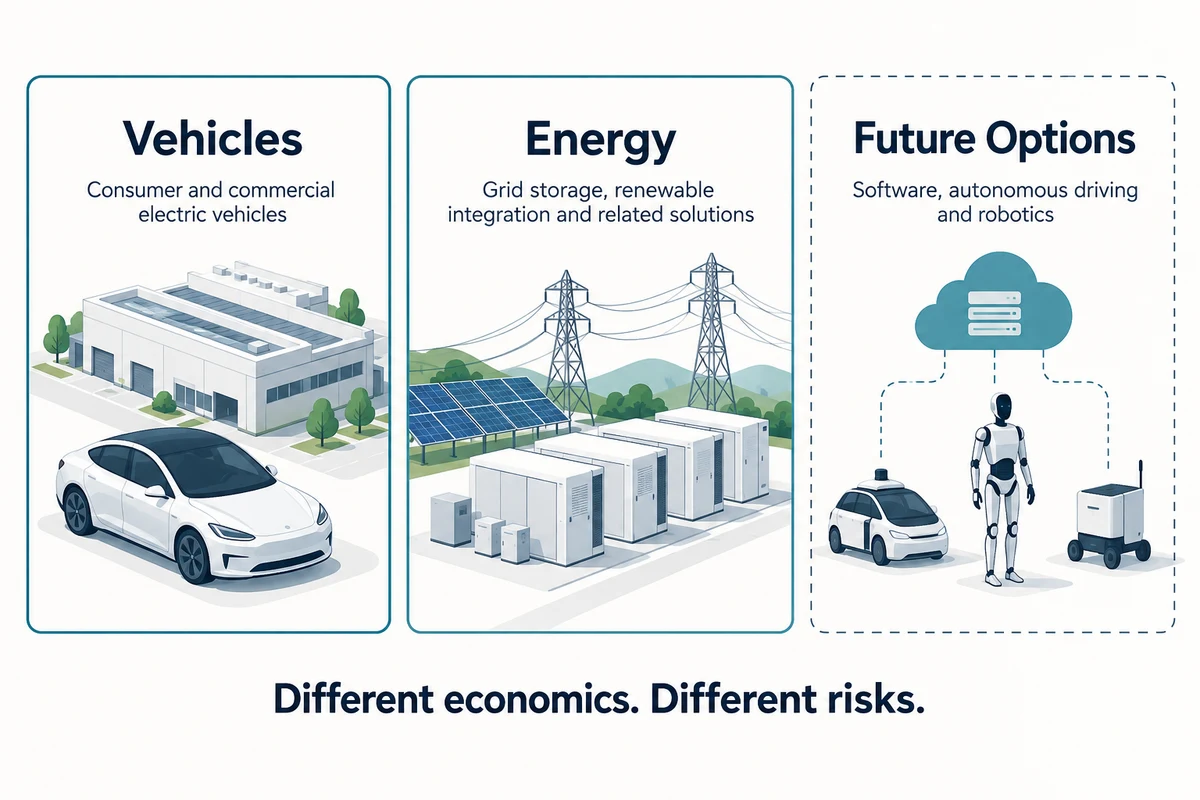
Automotive sales depend not only on volume but also on actual selling prices, costs, and the ability to sustain pricing. For energy, deployment volumes should be considered alongside the timing of revenue recognition under contracts and profitability. For software, autonomous driving, and robotics, distinguish revenue already being generated from business opportunities that still need validation. Do not aggregate these businesses on the assumption that every future business is already producing substantial standalone profits.
The quarterly results in the Q3 Update released on October 21 are as follows. Amounts are in millions of U.S. dollars; EPS is in U.S. dollars. Operating margins are calculated as operating income ÷ revenue. GAAP and non-GAAP net income are not mixed.
| Metric | Q3 2026 | Q2 2026 | Q3 2025 |
|---|---|---|---|
| Revenue | 28,046 | 28,236 | 28,095 |
| Operating income (GAAP) | 718 | 398 | 1,624 |
| Operating margin (CoinPop calculation) | About 2.56% | About 1.41% | About 5.78% |
| Net income attributable to common stockholders (GAAP) | 787 | 1,114 | 1,373 |
| Diluted EPS (GAAP) | 0.22 | 0.32 | 0.39 |
| Net income attributable to common stockholders (non-GAAP) | 1,697 | 1,153 | 1,770 |
CoinPop analysis: Third-quarter operating income of $718 million improved from $398 million in the previous quarter but was below the $1,624 million recorded in the same period last year. Beating delivery estimates and recovering core-business profitability year over year are separate issues. The difference between GAAP net income of $787 million and non-GAAP net income of $1,697 million should also be read alongside the adjustment items.
What might be missed by classifying Tesla solely as an automaker or an AI company?
Comparing Tesla only with traditional automakers may overlook the options offered by new businesses, while viewing it solely as an AI company may overlook manufacturing costs, capital requirements, and service responsibilities. Comparisons should use the same accounting period, GAAP basis, and share dilution basis, and should not double-count automotive earnings and unvalidated future earnings. This article does not force a list of peer multiples with mismatched benchmarks.
3. Growth investment and free cash flow: cash after investment differs even when there are profits
Third-quarter standalone operating cash flow was $6,263 million, capital expenditures reported by the company were $4,732 million, and free cash flow was $1,531 million. FCF as defined by the company is operating cash flow − capital expenditures, and 6,263 − 4,732 = 1,531, which reconciles. These are standalone figures for Q3 2026 and are not mixed with the first-half totals discussed earlier. Cash, cash equivalents, and short-term investments totaled $45,447 million at quarter-end.
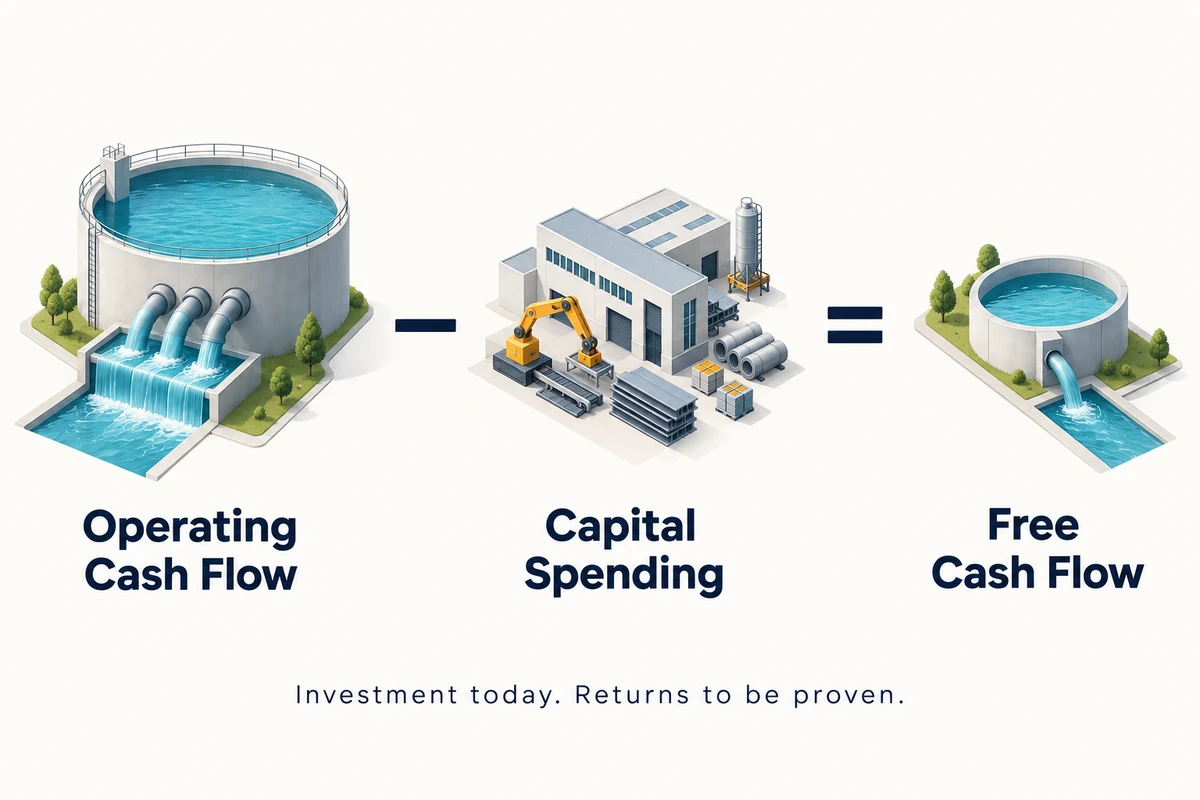
The previous second-quarter 10-Q included the company’s outlook that capital expenditures could exceed $25 billion in 2026. This figure should not be treated as a confirmed expense or the latest realized amount. Separate actual third-quarter investment from the company’s future outlook, and track when the investment is recovered as repeatable cash generation per share.
Cash flow in a single quarter is affected by inventory, accounts payable, and the timing of customer payments. Distinguish temporary working capital effects from repeatable cash generation, and separately consider both the cash savings from stock-based compensation and the potential dilution of existing shareholders.
4. Is Tesla stock attractively priced? Work backward from expected earnings
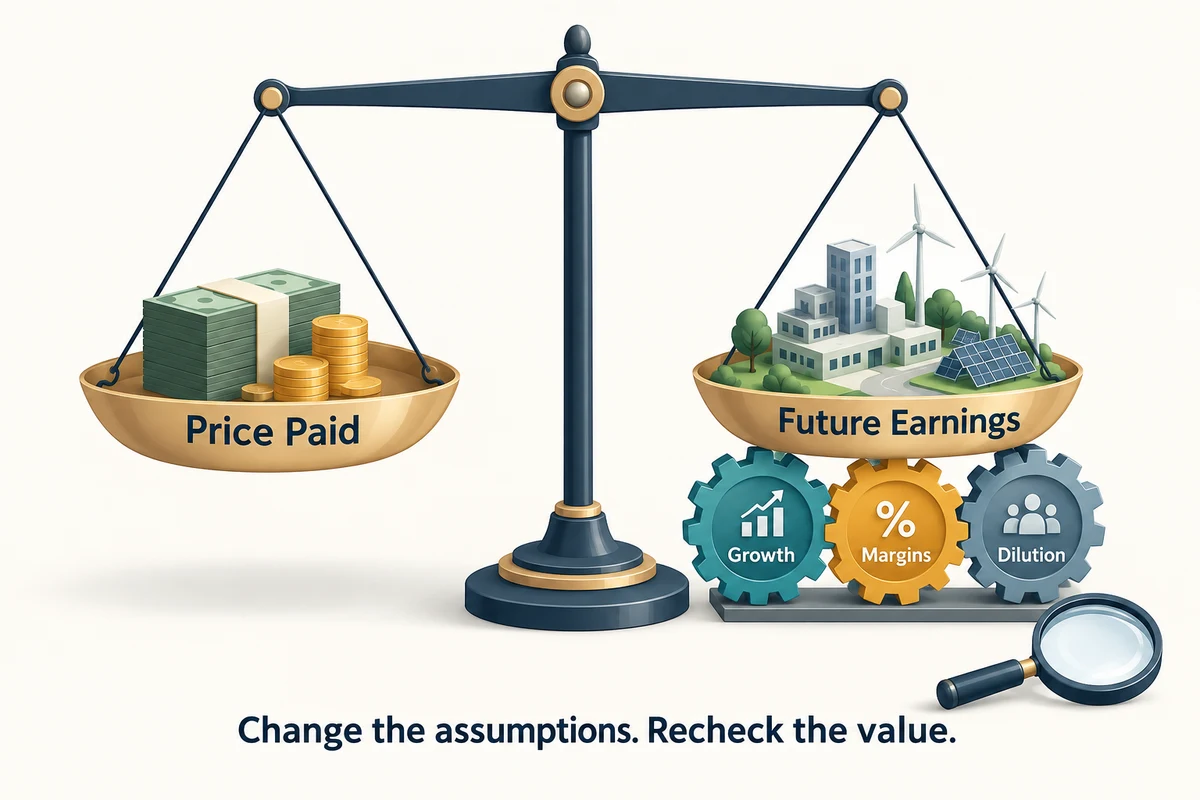
A good business and a good investment price are not the same thing. Valuation involves checking what growth is required, how much investment it will take to achieve that growth, and the price risk if results are slower or smaller than expected. Since the real-time stock price and peer multiples as of the same date have not been sufficiently compared, this article does not determine whether the stock is currently undervalued or overvalued, nor does it provide a real-time price target.
| Calculation assumptions | Assumed annual diluted EPS | Simple price-to-earnings ratio | Limitations of interpretation |
|---|---|---|---|
| Assumed stock price: $380 | 2 dollars | 190x | 380 ÷ 2. Not an actual forecast |
| Same assumed stock price | 4 dollars | 95x | The valuation multiple may remain burdensome even if earnings double |
| At the same assumed share price | 8 dollars | 47.5x | Separately assess when earnings are realized, how long growth can continue, and the risks |
The EPS above is not a forecast for any specific year or company guidance. A fair price today cannot be determined solely by dividing earnings in the distant future by the current share price; time value, further dilution, and reinvestment must also be considered. Conversely, a low multiple is not evidence that a stock is cheap if earnings are declining or one-off.
Interest rates can affect the discount rate applied to future cash flows and the returns investors demand. To understand this process, see How to distinguish FOMC decisions from the dot plot. A rate cut does not automatically guarantee a rise in Tesla’s share price. The relationship between inflation releases and rate expectations is explained separately in CPI vs. PCE: Differences and how to interpret the releases.
Another example of separating a company’s growth from a stock’s investment appeal is available in Nvidia’s AI earnings, cash flow, and share repurchase analysis. Rather than simply comparing two companies with different business models at the same multiple, compare the assumptions required for each to generate cash and create value per share.
5. Is it worth investing now? Three conditions that could change the assessment
Conditional conclusion: Tesla is a company to consider for its growth opportunities in both automotive and energy, as well as its future businesses. In the third quarter, operating profitability and cash after investment improved from the previous quarter, but the year-over-year decline in operating income and substantial investment spending remain concerns. The case for considering an investment becomes stronger when repeatable profitability, cash generation, and per-share growth after dilution continue, and when the price does not require only optimistic assumptions. Earnings results alone do not lead to a buy conclusion.
| Analysis scenario | Conditions to check | Investment consideration | Why it could be wrong |
|---|---|---|---|
| Positive path | Management of selling prices and costs, margin recovery, energy profitability, and progress in recouping investments | Assess whether growth translates into earnings and cash per share | Even if the business improves, that improvement may already be fully reflected in the price |
| Middle path | Volumes hold steady, but costs and investment offset the results | Wait for further results and assess the gap between expectations and actual performance | Current indicators may reflect long-term investment performance with a lag |
| Risk path | Price competition, low margins, commercialization delays, and regulatory, dilution, and investment burdens | Reassess growth assumptions and valuation concerns | New products or cost improvements could also mitigate risks |
The categories above are an analytical framework for assessing possibilities; they do not predict the probability of occurrence or the direction of the share price. An analysis that presents only the market size of autonomous driving and robotics while omitting actual paid usage, profitability, and legal liability is insufficient. Conversely, assigning zero value to all future businesses based solely on current automotive profitability is also an assumption.
What matters to different readers?
Readers considering Tesla for the first time should first separate positive delivery figures from an assessment of the company’s value. Existing shareholders should review whether their original investment thesis still holds and assess the concentration risk of holding the same stock. Readers approaching an earnings event should consider the possibility of increased volatility and their own capacity to withstand losses. For Korean investors, exchange rates, currency conversion, and trading costs also affect actual returns, in addition to the share price in U.S. dollars.
6. A checklist for the next quarter
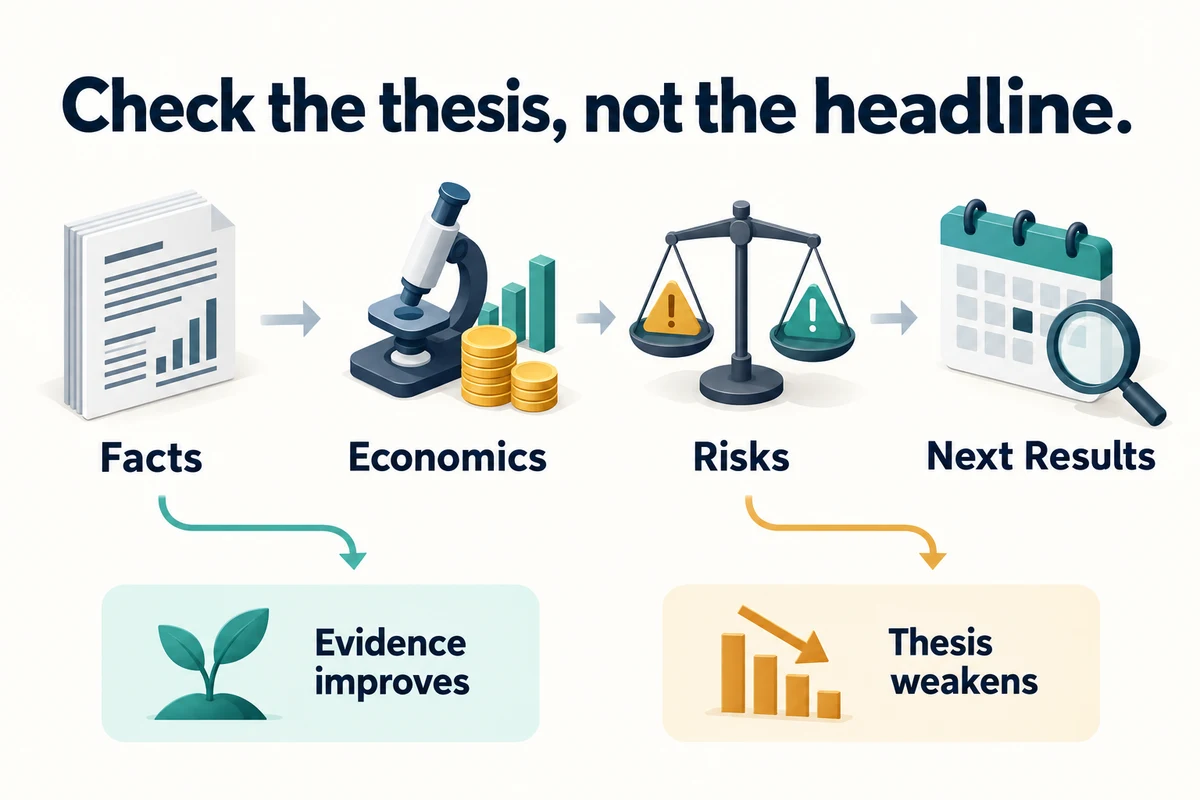
- Profitability: How have automotive pricing, product mix, costs, and operating margins changed?
- Earnings quality: Were non-operating income and expenses, taxes, stock-based compensation, and GAAP/non-GAAP adjustments distinguished?
- Cash and investment: Were operating cash flow, capital expenditures, and working capital compared over the same period?
- Energy: Are the timing of revenue recognition for deployments and profitability meeting expectations?
- Future businesses: Were confirmed paid usage and commercialization distinguished from management plans?
- Per-share value: Were increases in diluted shares outstanding and the risk of additional financing taken into account?
- Price: Were the timestamp of the latest share price and the earnings period aligned, and does the assessment hold under different assumptions?
If Tesla deliveries increase, will the share price also rise?
Not always. Existing market expectations, selling prices and margins, the outlook, and interest rates all play a role. Deliveries exceeding expectations are one data point, not a buy signal.
Have the third-quarter results already been announced?
Yes. Tesla released its third-quarter financial results on October 21, 2026. This article has been updated with the actual reported figures for operating income, GAAP/non-GAAP net income, operating cash flow, capital expenditures, and FCF. The latest share price and valuation should be checked separately.
Should Tesla be valued only using automotive-company multiples?
Rather than using a single classification, it is more useful to separate cash generation by business and additional growth opportunities. Unverified future earnings should not be treated as equivalent to confirmed earnings; account for when they may be realized, additional investment, competition, and regulatory risks.
Are tokenized Tesla products or equity-linked derivatives the same investment?
Not necessarily. Common shares held in a brokerage account and tokens or derivatives may differ in voting rights, dividend treatment, redemption, custody, and issuer risk. For more on distinguishing product structures, see the explanation of the rights and risks of tokenized stocks. This article analyzes TSLA common stock.
Sources, scope of verification, and conflict-of-interest disclosure
- Primary sources: Tesla’s third-quarter 2026 operational update linked in the article, the company’s compiled estimates as of 2026-09-29, its third-quarter 2025 operational update, and its SEC 2026 second-quarter 10-Q.
- For additional earnings and filings: Tesla Investor Relations. Company schedules and outlook may change.
- Cross-check with independent reporting: interactive investor’s 2026-10-05 analysis, Axios’s 2026-10-02 report. The article’s key figures and calculations are based on primary sources; it does not adopt the investment opinions of other media outlets as its own.
- CoinPop’s contribution: comparisons with estimates, the previous quarter, and the previous year; limitations in interpreting the differences between deliveries and production; distinctions between GAAP earnings and cash after investment; and valuations and scenarios with disclosed assumptions.
This article contains no exchange sign-up or affiliate CTA. It is an analysis based on corporate filings and does not cite the author’s holdings or investment experience as evidence. Stocks can result in a loss of principal and are exposed to currency, business, competition, policy, regulatory, and management risks. The explanatory image is a conceptual illustration created by CoinPop; it is not official company material, an actual screen, or proof of returns. When new official materials become available, the facts and verification date in this document will be updated as needed.